KLCC & TRX · Buying to rent
Neither address guarantees a good investment. The useful comparison is what you pay, what a tenant will actually pay you, and what remains after the bills.
What are you paying for in each location?
For a completed KLCC condo, focus on evidence from that building: achieved rents, maintenance history and competing units. A tower view is a feature, not proof that tenants will cover the price premium.
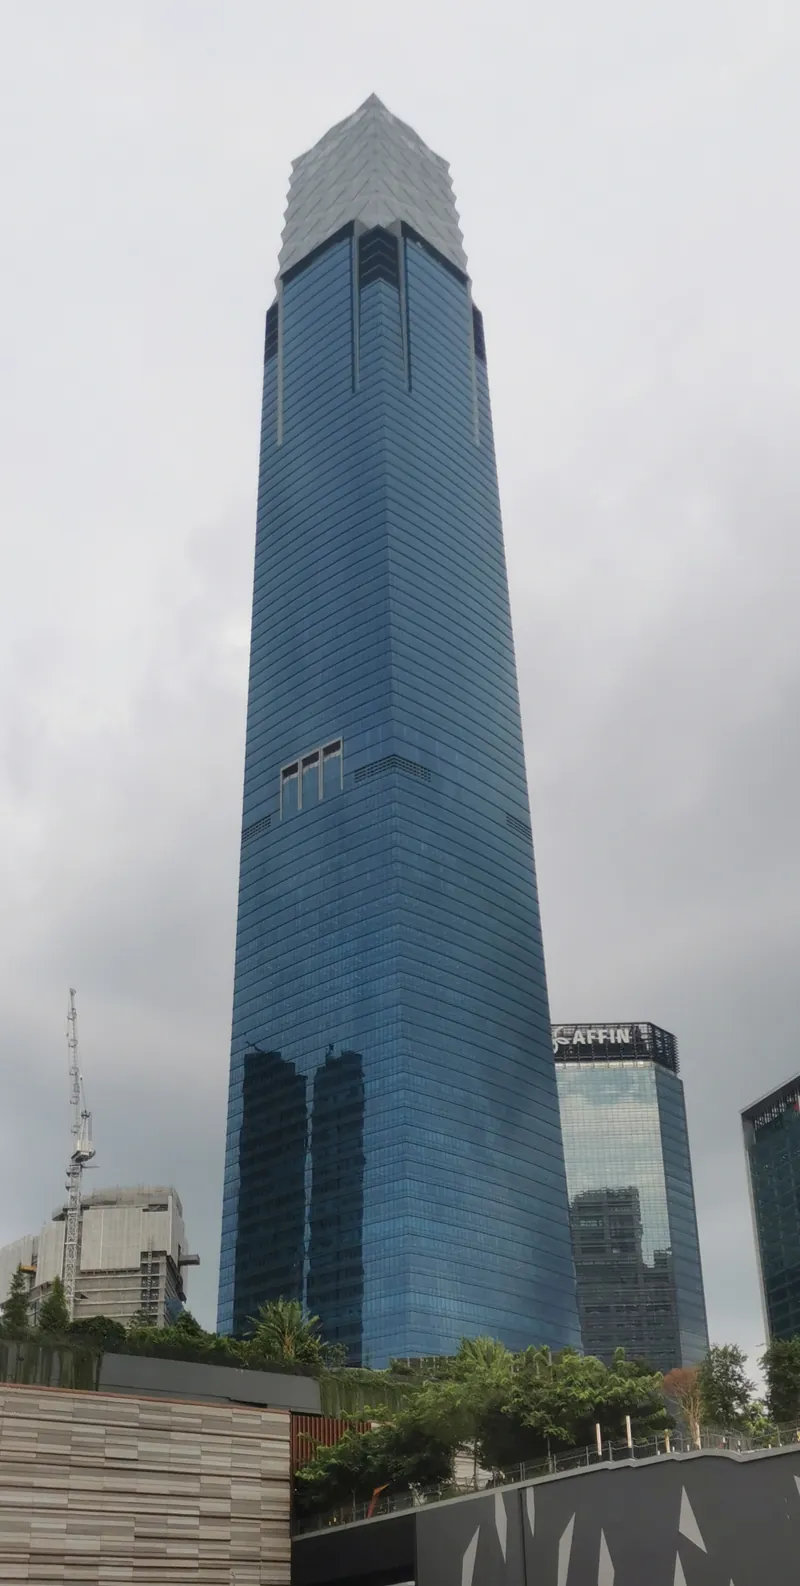
At TRX, ask whether the specific home benefits from the district’s offices, retail and transport connections. The official district overview explains the setting; it does not establish residential rental demand or returns. “Near TRX” and convenient access are different things.
Compare homes of similar size, condition and furnishing. A completed apartment with a tenancy history and a home still awaiting completion are not equally ready to produce rent. Keep projected future income separate from rent already being collected.
Illustrative figures only
Higher rent can still mean a lower yield
These fictional units could be in either area. They are not KLCC or TRX market prices. Both assume 11 paid months and one empty month in a year.
| Input or result | Unit A | Unit B |
|---|---|---|
| Purchase price | RM1m | RM1.25m |
| Monthly rent | RM4,000 | RM5,000 |
| Gross yield* | 4.8% | 4.8% |
| Rent collected | RM44,000 | RM55,000 |
| Costs and reserves | RM12,000 | RM18,000 |
| Left before loan and income tax | RM32,000 | RM37,000 |
| Net cash yield on price** | 3.20% | 2.96% |
*Gross yield uses 12 months of rent divided by purchase price, before vacancy and costs. **Here, net cash yield means rent collected less the stated costs and reserves, divided by purchase price. It is not a return on your deposit or a formal valuation.
The cost assumptions include RM7,200 for A and RM10,800 for B in annual maintenance and sinking fund payments. The remaining RM4,800 and RM7,200 cover assumed property charges, insurance, letting expenses and repair or replacement reserves. Replace these amounts with actual bills and estimates; they are not standard local charges.
Unit B leaves more ringgit, but requires a higher purchase price. A has the higher percentage yield in this example. Neither calculation includes purchase fees, initial furnishing or resale costs. Adding those upfront costs to the denominator would reduce the yield on total outlay.
For the building bill, see our maintenance fees and sinking funds guide.
Yield is not money left after the mortgage
Suppose your loan repayments are RM4,000 a month for A and RM5,000 for B. These are assumptions, not bank quotations. Annual repayments become RM48,000 and RM60,000, leaving cash shortfalls of RM16,000 and RM23,000 after the costs and reserves above, before income tax.
Repayments include principal as well as interest, so a cash shortfall is not the same as an accounting loss. You still need money available to fund it. Use the bank’s actual repayment schedule before making an offer.
How much room is there for a bad year?
For Unit A, change one assumption at a time while keeping everything else fixed:
Rent falls 10%
RM3,600 × 11 paid months leaves RM27,600 after the same costs and reserves.
Another empty month
Ten paid months at RM4,000 leave RM28,000 before the loan and income tax.
An extra repair
A RM5,000 bill beyond the existing reserve reduces the base RM32,000 to RM27,000.
These are separate tests. Several problems happening together would reduce the result further.
What should support the real numbers?
Ask for recent achieved rents from comparable units, including size, furnishing and tenancy date. Advertised rents show what owners want, not necessarily what tenants agreed to pay.
Use building accounts and current bills for recurring costs. For purchase price context, review comparable completed sales where available; NAPIC’s market publications provide broader background, not a valuation of your unit. Our KLCC subsale guide covers the purchase checks.
Choose on evidence, not an area winner. Compare the same numbers for both homes, including what you can fund during vacancy. For location context, read the TRX neighbourhood guide and KLCC living guide.
Educational examples, not personalised investment advice or a forecast.